"One of the UK's leading specialists in financial mis-selling…"
The Times
LCM Family Limited, formerly LCM Wealth Management Limited, entered administration in April 2026. The Financial Services Compensation Scheme (FSCS) is currently accepting claims while it investigates whether affected clients meet the qualifying conditions for compensation.
If you received investment advice from LCM and have since suffered a loss, you may be unsure whether there is anything about the original recommendation that should now be looked at more closely.
LCM Family Limited provided regulated financial advice and investment services. On 14 April 2026, the FCA placed an immediate restriction on all its regulated activities. Just two weeks later, on 28 April 2026, the company entered administration.
Information published by the administrators indicates that LCM had around 300 individual clients across 50 family groups and approximately £89 million of assets under its administration.
Before LCM entered administration, administrators reported there was a sudden increase in complaints relating to call warrants that had become worthless.
The reported complaints are significant because these products can expose investors to substantial losses, including the possibility of losing the full amount invested.
An investment losing money does not, by itself, mean that the advice was negligent.
What matters is whether the recommendation was appropriate for that client when it was made. That means looking at factors such as:
For higher-risk investments, an important question is whether the client had the capacity to withstand the potential loss and understood the level of risk involved.
Request a free call back and one of our team will call you back for a no-obligation chat
Call warrants are structured investments whose value depends on certain conditions being met. If those conditions are not met before the warrant expires, the investment can become worthless, and the investor may lose the full amount invested.
That possibility of a 100% loss is very different from normal fluctuations in investment value. An investor would need to be able to absorb the loss of the entire amount committed to the product.
For someone advised to invest in this type of investment, a key question is whether that level of risk was made clear before they invested. The recommendation and product information should help show how the investment was explained and what the client was told about the potential outcome.
If you are concerned about advice you received from LCM, keep any documents that show what information was gathered about you and why the investment was recommended.
The most useful records are likely to include:
Together, these records can help reconstruct the advice process. They will evidence what LCM knew about you, what it recommended and the reasons given for that recommendation.
We keep you informed throughout the process, from your initial case review through to pursuing compensation. Our specialist solicitors will assess the available evidence, explain the next steps and manage the claim on your behalf.
If we are able to take on your LCM Family claim, we may be able to act under a No Win, No Fee agreement, meaning you would not normally pay legal fees upfront.
Before you decide whether to proceed, we will explain how the agreement works, what fees may apply if your claim succeeds and any circumstances in which you could be responsible for costs.
Experience handling financial mis-selling, investment and professional negligence claims.
Compensation recovered for clients across financial mis-selling and negligence claims.
For cases accepted by the firm.
Where available, legal fees are explained clearly before you decide whether to proceed.
Claims are assessed and managed by specialist solicitors.
Neglect Assist is operated by Wixted & Co Solicitors, regulated by the SRA.
These cases did not involve LCM Family, but they illustrate the kinds of suitability issues that can arise when an investment recommendation does not reflect the client's circumstances or attitude to risk.
Mr & Mrs S sold business properties to fund their retirement and sought low-risk investment options. Their bank advised them to invest in a high-risk managed fund, resulting in minimal returns. We secured £50,000 in compensation for them.
Mr & Mrs C asked for a secure investment to fund their retirement. Despite this, they were advised to invest £280,000 into a high-risk bond. When the investment fell in value, we acted on their behalf and successfully recovered £37,500 in compensation.
After selling their family home, Mr & Mrs A sought to invest cautiously to support their retirement. Their financial adviser recommended high-risk funds—without fully explaining the risks. Their investment dropped in value, but we successfully recovered over £30,000 in compensation.
Yes. LCM Family Limited previously traded as LCM Wealth Management Limited, so former clients may recognise either name in their advice or investment paperwork.
LCM Family entered administration on 28 April 2026 after the FCA had restricted its regulated activities earlier that month. Administrators also reported an increase in complaints involving call warrants that had become worthless.
Administrators reported complaints involving call warrants. These high-risk products can expose investors to losing the full amount invested if the required conditions are not met. For example, if the underlying stock price stays below the strike price when the warrant expires, the warrant becomes completely worthless.
No. Investment loss alone does not prove that advice was negligent. The key issue is whether the recommendation was appropriate for your circumstances when it was made.
Useful documents may include your fact find, recommendation or suitability letter, product information and records showing your financial circumstances at the time of the advice.
The FSCS is currently accepting claims relating to LCM Family while it investigates whether claims meet the qualifying conditions for compensation.
The working position is that the FSCS can pay up to £85,000 per eligible person, per firm for qualifying investment claims. The amount available depends on eligibility and the loss accepted by the FSCS.
The FSCS limit may not cover the full amount of a larger loss. Whether any other route is available will depend on the individual circumstances and any other parties involved.
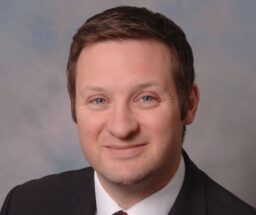
Tim qualified as a solicitor in 1997 and has more than 25 years of experience advising clients on professional negligence, financial mis-selling and complex civil litigation matters. He oversees the firm’s professional negligence cases and advises on case strategy.
Tim has reviewed this page to help ensure the legal information is accurate, up to date and relevant to individuals considering a potential claim.
If you received investment advice from LCM Family or LCM Wealth Management and are concerned about a loss, we can review the information you have and let you know whether there may be grounds to investigate the advice further.
Provide your details to start your free eligibility check. You’ll be guided through a few short questions so we can direct you to the right specialist and assess how we can help.
You do not need legal representation to make a financial services claim. You can complain yourself at no cost and under FCA rules, the financial services provider must provide a response. If you feel this is unsatisfactory, you can complain to the statutory redress bodies, the FOS and FSCS who can award you compensation. This is a free service.
The information appearing within this website does not constitute legal advice and is provided for general information purposes only. No warranty, whether express or implied, is given in relation to such material, and we do not accept any liability for reliance on it.
Neglect Assist is a trading style of Wixted & Co Solicitors which is authorised and regulated by the Solicitors Regulation Authority (SRA) A copy of the SRA handbook can be obtained from www.sra.org.uk. Wixted & Co Solicitors, 57 Putney Bridge Road, London SW18 1NP.
Registered number 06243291. VAT number 788 6929 41.
© 2025 Wixted & Co Solicitors